
RTX Corp., formerly Raytheon Technologies, raised its full-year outlook for a third straight quarter as the Western rearmament supercycle gathers momentum.
Wall Street welcomed the earnings update: RBC Capital Markets called the results "strong," Goldman Sachs highlighted a "solid quarter" with higher guidance, and UBS pointed to "accelerating defense growth."
The Tomahawk cruise missile maker reported third-quarter earnings earlier and now expects 2026 adjusted earnings of $7.65 to $7.75 a share, up from a previous ceiling of $7.25. Even the lower end of the revised range exceeds the average analyst estimate tracked by Bloomberg. RTX also boosted its sales and free cash flow forecasts.
All three of RTX's main operating units reported double-digit organic sales growth in the quarter. Adjusted earnings topped $2.26 a share, beating expectations, though the figure included a 25-cent gain from recovering tariffs the Supreme Court struck down earlier this year.
Goldman Sachs aerospace and defense analyst Noah Poponak shared his initial view with clients: "Solid quarter and guidance raised."
More color from Poponak:
Bottom Line: RTX 3Q26 results came in ahead of consensus across key metrics, with revenue and segment EBIT ahead in all three segments. Collins EBIT includes +$250mn of IEEPA recovery, and Pratt EBIT includes +$160mn of IEEPA recovery. The company raised its 2026 guidance across the board, with organic revenue growth now at 10%-11% (vs. 8%-9% prior) and midpoint increases of 2% for revenue, 7% for EPS, and 6% for free cash flow, partially operational and partially IEEPA.
Details: 3Q26 adjusted EPS is $2.26 vs. FactSet consensus of $1.78. Revenue of $24.97bn is 4% ahead of consensus. In the segments: Pratt revenue is up 10% yoy organically, with OE down 5%, aftermarket up 21%, and military up 2%. Collins revenue is up 12% yoy organically, with OE up 23%, aftermarket up 9%, and defense up 7%. Raytheon revenue is up 14% organically. Adjusted segment operating margin of 15.2% is above consensus at 13.2%; with all three business segments ahead, although there are IEEPA recovery benefits and large one-time items. 3Q26 free cash flow of $2,119mn is above consensus at $1,730mn, and includes ~$300mn of IEEPA recovery.
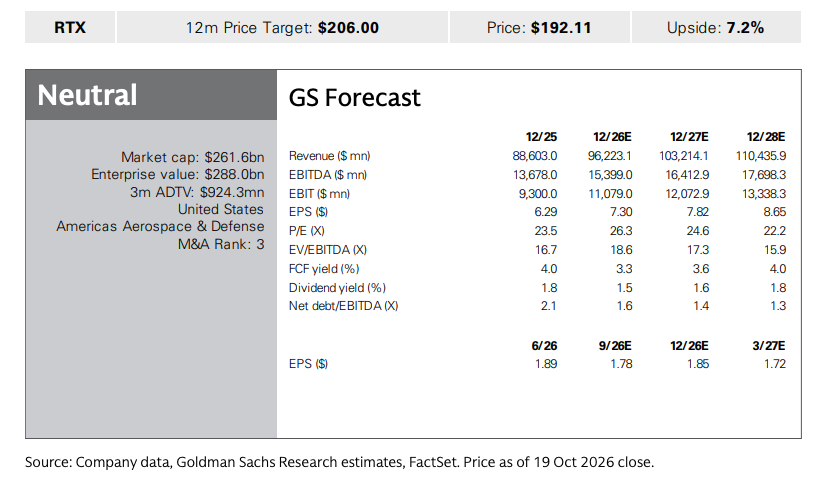
RTX provided updated 2026 guidance, which includes adjusted sales of $97.0 - $97.5bn ($95.0 - $96.0bn prior; consensus at $96.28bn), organic sales growth of 10-11% (8-9% prior), adjusted EPS of $7.65 - $7.75 ($7.10 - $7.25 prior; consensus at $7.26), and FCF of $9.0 - $9.2bn ($8.50 - $8.75 prior; consensus at $8.7bn).
Separately, UBS aerospace and defense analyst Gavin Parsons outlined that the earnings results indicate the defense rearmament supercycle is "accelerating."
Parsons explained:
Strong headline results, still a broad-based beat adjusting for one-timers like IEEPA reversal. Revenue grew 12% organically, and RTX raised guidance for sales, EPS and FCF. Backlog reached a record $340bn following more than $81bn of awards, highlighted by $37bn of multi-year Tomahawk and AMRAAM awards. Commercial aerospace demand also remains strong, no signs of aftermarket slowdown with Collins/Pratt aftermarket +9/21%. 8% segment EBIT beat adjusting out $250mn of Collins IEEPA recovery, $160mn at Pratt, and a $85mn one-time benefit at Raytheon (margins 18.3% at Collins, 8.8% at Pratt, and 13.1% at Raytheon) - beat in all 3 segments. We expect investors to focus on the sustainability of aftermarket demand, the multi-year defense topline, Pratt OE mix headwinds, Raytheon margin drivers, and the bridge to free cash flow and guidance.
Notable Pros: Organic revenue +12% (Collins +12%, Pratt +10%, Raytheon +14%), adj. Segment EBIT +21% with 110bps of margin expansion, backlog at a record $340bn (+36% yoy), commercial aftermarket remained strong (Collins +9%, Pratt +21%), and guidance was raised across sales, EPS, and FCF.
Notable Cons: Pratt commercial OE declined 5% due to unfavorable large engine mix, $363mn customer bankruptcy charge at Pratt.
How did the results compare vs consensus expectations?
Beat on Adj. sales, Adj. EBIT, and Adj. EPS.
2026 Guidance
Adjusted sales: $97.0bn-$97.5bn ($95.0-$96.0bn prior) vs. cons at $96.3bn
Organic sales growth: 10-11% (8-9% prior)
Adjusted EPS: $7.65-$7.75 ($7.10-$7.25 prior) vs. cons at $7.26
FCF: $9.0bn-$9.2bn ($8.50bn-$8.75bn prior) vs. cons at $8.7bn
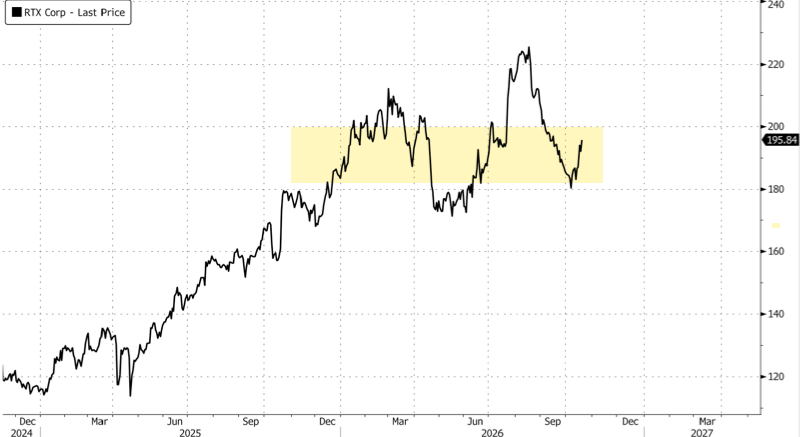
RTX shares are up 1.4% in early US cash trading, though the stock remains within the $180 to $220 trading range that has held throughout the year.
The broader defense sector has come under pressure as investors weigh the implications of rising odds of Democratic control of the Senate.
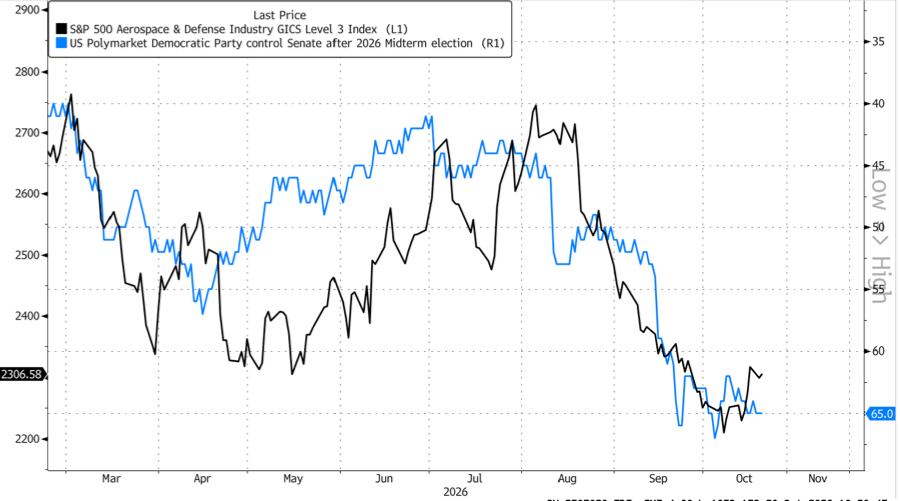
Will defense stocks rally if a Democratic Party midterm shock is not as bad as previously thought?