
Nike shares are down nearly 10% in pre-market trading in New York after the struggling athletic footwear and apparel company warned its sales slump will deepen and unveiled a restructuring that will eliminate jobs.
As of Thursday's close, year-to-date performance had been absolutely abysmal, with shares down 45%. The extended decline could now put the stock on track for its worst annual loss on record.
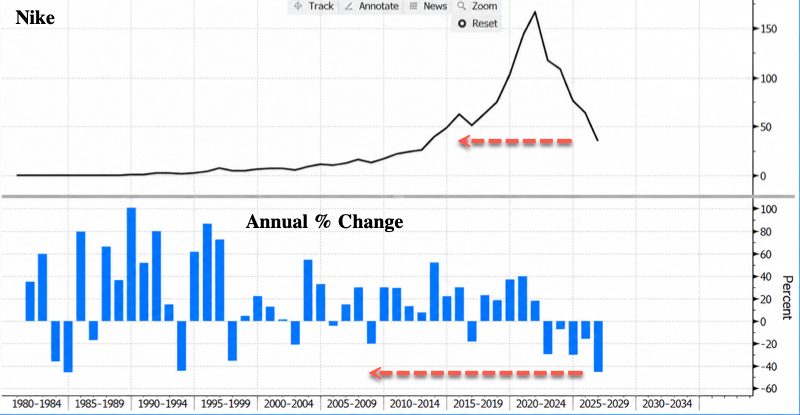
The decline follows the sportswear giant's earnings release after hours on Thursday, when it stated that it now expects revenue to decline by a high-single-digit percentage this fiscal year, substantially worse than the 2.4% drop analysts tracked by Bloomberg forecast.
Nike spent years catering to woke culture while neglecting to stay ahead of the industry as competitors ate into its market share. It now plans to fold its Greater China unit into its broader Asia Pacific division and combine Latin America with North America.
This restructuring is expected to deliver $2.5 billion in savings over five years while generating roughly $1 billion in pretax charges.
CEO Elliott Hill wrote in a memo to investors that this restructuring "will require fewer roles over time."
Hill, approaching his third year as CEO, has focused on rebuilding retail relationships and organizing Nike around individual sports.
The ugly guidance on Thursday comes after BofA retail analyst Lorraine Hutchinson downgraded the stock last week and warned that its "turnaround is taking longer" than expected.
UBS retail analyst Jay Sole wrote in a note shortly after earnings about "why it's still not time to buy Nike" and maintained a "Neutral" rating on the stock, lowering his 12-month price target to $34 from $42.
Sole explained:
The key downside risk is Nike's downward EPS revision cycle may persist:
The pivotal Nike question remains "Is all the 'bad news' now priced in?" Despite the pullback in Nike's stock price, we still don't see a good entry point. Nike's stock price is still not cheap at ~28x our FY27 EPS estimate, in our view, and this suggests a solid rebound remains priced in. We continue to see a balanced upside/downside skew. The main upside risk is Nike's November Analyst Day convinces the market the stock's downward earnings revision cycle has ended and investors are willing to put a peak multiple on their FY27 EPS outlook. The main downside risk is the rebound takes much longer than the market anticipates and therefore the downward earnings revision cycle may not be over.
We see 3 reasons NKE's downward EPS revision cycle may not be over:
- The market may be underestimating the negative impact on unit demand as Nike tries to reduce discounts. Nike's FY27e gross margin likely hits a 20-year low. To drive a gross margin recovery, Nike would have to significantly reduce discounts. We believe the elasticity of demand in this situation could be greater than 1. However, we don't think Nike's -HSD% FY27 revenue guidance incorporates this. We believe the sales guide reflects weak demand, elevated inventory levels and a major China pullback. Thus, we see risk pulling back on promotions drive another big drop in sales in FY28.
- The market may be underestimating the negative impact on sales from Nike having to reset its Sportswear and Jordan businesses. Nike brand Sportswear plus Jordan Streetwear equates to roughly 60% percent of NKE revenues. 1Q27 sales in these categories fell at least -LDD% y/y. We believe fashion trend shifts and a lack of brand momentum are hurting Nike in a major way. The risk is Nike can't impact these trends soon and this leads to more pressure well into FY28.
- The market may be underestimating the negative impact on margins if sales slow. Nike announced its 3rd big cost adjustment program since 2020. The concern is Nike may not have very many easy cost reductions left to make and will need to ramp up investment in order to grow. If so, more downside revenue surprises could pressure margins more than we and the market expect.
We lower our FY27-FY29 EPS estimates ~4-6%, respectively:
We lower our FY27 and FY28 revenue growth forecasts related to Nike's reset of its Jordan and Greater China businesses. We note Nike mgmt. expects these actions to weigh on revenues over FY27 and into FY28. Additionally, we now anticipate greater fixed cost deleverage driven by our weak topline forecasts. Lastly, we now model a higher share count given lower than expected buybacks during Q1 and expected going forward given our reduced FCF forecasts. This is partially offset by a reduced SG&A forecast given Nike's newly announced Pace cost savings initiative. These factors are the main drivers of the 4-6% reduction in our FY27-FY29 EPS estimates, respectively. Please find much more forecast detail inside.
Valuation: We lower our PT 19% to $34 and remain Neutral:
Our $34 PT is based on 18x our $1.90 FY29 EPS estimate. Our prior was based on 21x our old $2.00 FY29 EPSe. We lower EPS estimates and the P/E used to value NKE given our view fundamental trends in China and Nike's Jordan business are weaker than previously thought. Our multiples analysis indicates a $34 PT puts NKE's valuation in-line with peers in terms of P/E, P/Sales, & FCF yield (Fig. 6). Our DCF analysis also supports a $34 valuation (Fig. 9).
Other Wall Street analysts offered their first take assessments, courtesy of Bloomberg:
Morgan Stanley (underweight, PT $27 from $31)
- Nike's 1Q print "did little to change" our underweight rating, "with negative EPS revision & valuation de-rating risk remaining intact," analyst Alex Straton says
- "The Investor Day is the next key catalyst, with our focus on the magnitude of further topline right-sizing"
Guggenheim (buy, PT to $50 from $60)
- "With yet another downward revision, the questions remain when guidance cuts will represent the band-aid rip versus slow bleed as they continue to debate the path potential stabilization ahead," analyst Simeon Siegel says
Vital Knowledge
- Analyst Adam Crisafulli says Nike's first-quarter numbers were fine, but the guidance "is pretty ugly"
- Expectations "were very low" after earlier results from peers Dick's Sporting Goods and JD Sports, but the inability of management to get a handle on the business "is going to grate on investors (and might even start spurring talk about potentially changing the CEO position, even though Hill has only been in the role for ~2 years)."
CFRA (buy, PT $62)
- "We are disappointed with the results and expected better full-year EPS guidance," writes analyst Zachary Warring
- Says growth in North America was more than offset by continued deterioration in Greater China and a sharp ongoing decline at Converse
According to Bloomberg data, 15 analysts are "Buy" rated on the stock, another 25 with "Holds," and 7 "Sells." The average 12-month price target is $40.
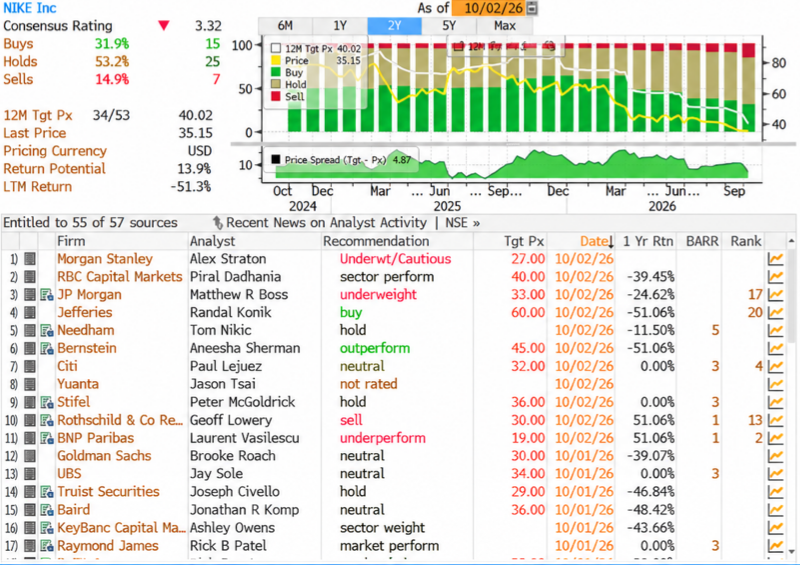
UBS Sole makes a great point: the stock is still not at the bottom.