
By Peter Tchir of Academy Securities
Diesel has become the “global” focus, rather than “just” the price of oil. We believe that is the correct focus, though we still see too much of the conversation focused on oil and too little attention given to the other distillates and downstream products, but let’s not quibble.
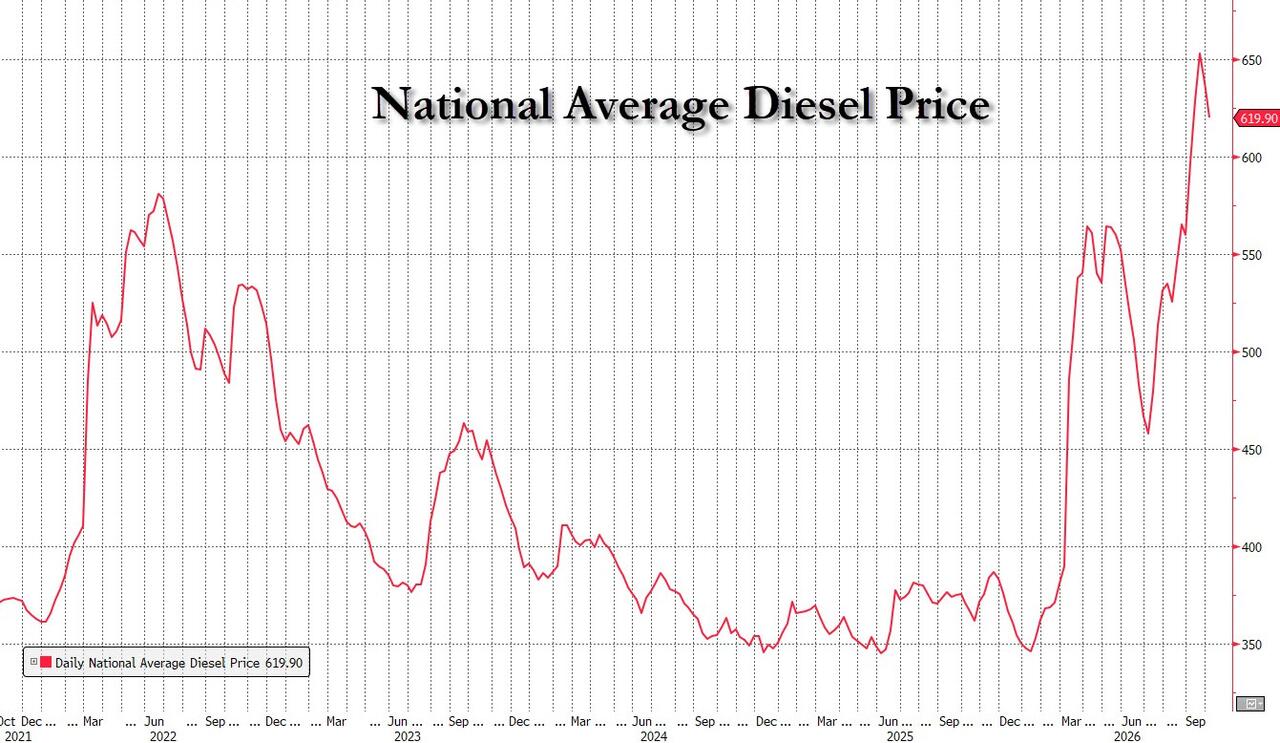
It is worth checking out the U.S. National Average Price of Diesel since 2022 so we can encompass both the Russian invasion of Ukraine and the start of this iteration of the conflict in the Middle East, primarily between the U.S. and Iran (with heavy involvement from Israel). The Gulf States have been impacted and there is an “almost” separate war between the Houthis, the Saudis, and others. “Almost” separate, in that for the moment it is being treated that way, at least publicly, from the U.S. perspective, but the conflicts are clearly interconnected.
This diesel index peaked (so far) at $6.53 on September 21st.
Europe’s Diesel
On October 2nd, the President announced that Europe was going to release some of its reserves, which was confirmed by Macron in his role as G7 chair.
European release is extremely important.
The discussion is about as much as 100 million barrels being released by the EU over the next 4 months. It would be a mix of diesel and oil (and presumably some other fuels held in reserve).
As with everything about Europe, it is a bit more complex than that. Germany was seen to be hesitating, while France seemed fully on board. Other countries have remained relatively quiet.
The International Energy Agency (the “IEA”) will meet this Wednesday to discuss what should be done. The focus is said to be on diesel, but it will cover the entire spectrum of what can be released and the timing of such release.
My understanding is that the IEA will make a determination of what should be released and when it should be released, but they do NOT control the release.
Each individual country has bought and paid for its own reserves. Each country controls whether it will release them or not, in accordance with the IEA recommendations.
Best Case.
- The IEA recommends 100 million barrels over 4 months, with diesel being a large chunk of that 100 million. Not only is diesel a large chunk, but it is also skewed to delivery in the first month or two.
- Each individual country immediately agrees to the recommendations and delivers its reserves as per the IEA plan.
There are at least two problems here, if not more.
Risks at the IEA level.
- Will the IEA say they need to perform some sort of study to determine the best steps? Will they really be prepared to act on Wednesday or will we get an “action plan” of next steps, rather than action? There is a risk that the IEA says they need more time to “study” the problem before they can recommend a plan. It would seem like a cop-out, but bureaucracies and studies go hand in hand. There are some in the industry who believe that is what some countries are hoping for. That the countries don’t have to let down the President, because their hands are tied by the IEA.
- The IEA could come in with much lower recommendations for release. If you “believe” that the war will be over shortly after the midterms (which is the President’s current messaging), then sure, release a lot because you will be able to start rebuilding reserves within a relatively short period of time. If, however, the IEA is worried that Russia and Ukraine are going to hit each other’s energy infrastructure more, that the Iran War will remain an issue for longer, or that there is risk in the Gulf beyond what has already occurred, they may want to release less. If you think things could get worse before they get better, you would want to keep more in reserve for that possibility.
Risks at the country level.
- Individual countries might just say no or decide to release on a different schedule (presumably smaller and slower than hoped for). If some smaller countries don’t participate, not a big deal. But if a country with a significant percentage of the reserves decides not to fully participate, not only would their contributions be lower, but you should expect other countries to follow their lead – meaning the entire release will be impacted significantly.
All of this could have been written on Friday morning. The best case hasn’t changed. The risks haven’t really changed. What has changed is the diesel deal that the President announced Friday afternoon. Will that deal affect the probabilities of the outcomes?
Russia’s Diesel
On Friday afternoon the President announced purchases of previously sanctioned Russian diesel.
The deal is clearly being framed as an effort to reduce the price of diesel in the U.S. Yet crude futures barely budged. Treasury yields didn’t do much. Even stocks failed to do much.
There are many reasons why the markets didn’t respond extremely positively. There are a lot of questions and issues with this deal.
- By the terms announced, Russia will deliver about 70k barrels per day in October. That rises to 125k in November and 240k in December.
- Estimates for U.S. daily consumption seem to be around 3.8 MILLION barrels per day. So, the Russian deal in and of itself is small relative to the size of the market.
- That level of exports from Russia is a fraction of the size of what they typically deliver this time of year (one estimate I saw is that it is about 50% lower than what they would normally export).
- Assuming Russia has the capacity, it will take time to organize the deliveries and move them.
So, the size of the deal is relatively small in the grand scheme of things, which is one reason markets may not have responded very positively.
- Diesel is fungible and the market is global.
- Russia was always going to export whatever diesel they could. Does it make some difference that it will go to the U.S. rather than elsewhere? Sure, assuming it makes it here. But the reality is that those who were expecting to get deliveries of Russian diesel will now have to bid up diesel prices elsewhere. Without export bans (which I think are an awful idea), this won’t move the needle on global prices for diesel, therefore limiting the impact on U.S. diesel prices.
- I do believe the Jones Act suspension will be extended, and I’m good with that.
Shifting who gets to buy what from whom in a global commodity has only limited ability to affect local prices. I will see if the diesel prices on the road from Tuscaloosa to Birmingham have dropped on Sunday since I saw the posted prices on Friday.
The size of the deal (small in the grand scheme of things), the ability of Russia to deliver on it (infrastructure attacks and shipping), and then the global vs local pricing, all mean the markets were right to give a relative yawn to this deal (at least at first blush).
Does One Deal Impact the Other?
This is where things get interesting.
Shortly after the Truth Social post announcing the deal, Zelensky posted a “cautiously frustrated” note on Twitter.
He did reiterate his willingness to back down on attacking Russia’s energy infrastructure if Russia would back off on what they are targeting in Ukraine.
- Could this deal be the incentive everyone needed to get to the table and form a plan to de-escalate the attacks between Russia and Ukraine?
- If an agreement can be hammered out that would take energy infrastructure off the table as a valid target (at least for now), then Russia’s ability to deliver above and beyond the terms of the deal announced would increase a lot.
- Could this force Europe to be more aggressive on its own plans to release reserves? Possibly.
- Could this derail the progress being made on releasing European reserves? From Academy’s Summit, our UK flag officers sounded very different this year from last year on how they see international defense and relationships. I think there is a realistic chance that Europe viewed itself as bending over backward to help the President on diesel (in their minds even if not in reality) and that this deal with Putin is a stab in the back. Let’s not forget, these leaders all need to get re-elected (and for many that is not going well), and releasing diesel to “help the U.S.” (yes it helps them too, but that isn’t the primary message) while watching Russia sell diesel to the U.S., may not play well with their electorate.
The jury is out, but:
- If this latest deal with Russia leads to an end of energy infrastructure attacks, we will see diesel prices back off further.
- If this smaller deal somehow derails Europe’s attempts to release its diesel reserves, the deal with Putin will have backfired.
All eyes should be on how Europe reacts to this. It is important that Zelensky left negotiations on the table in his note (which seemed carefully crafted to sound more like disappointment, with a measure of hope, rather than anger).
I think the markets were quick to digest the terms of the Russia deal itself (kind of a non-event), on Friday. I don’t think they were thinking at all about what this might do for the European diesel release – which is the bigger deal on the table.
Yields
The 10-year Treasury moved down from its highs of a 5.3% close on Monday (and 5.35%, which it touched on Wednesday and Thursday) to close the week virtually unchanged at 5.24%.
French bond yields peaked last Thursday (on a closing basis) and finished the week at 4.85%, about dead in the middle of its range for the past 10 days.
The MOVE index (VIX for bonds) came down to close at its lowest level in 2 weeks, but still quite elevated.
Treasuries and sovereign debt yields remain on our watch list. Both bulls and bears had enough price action to come into next week convinced they are right.
I think the impact David Zervos could have on the market is being underestimated.
While Bessent knows many high-profile players and is clearly plugged into central bankers across the globe, David brings direct connectivity to every major player in the Treasury market. If you want auctions to go well, his network may be even more valuable than Bessent’s.
@DavidZervosDC has become more active on Twitter since taking this role. He is probably worth following (especially since he has good taste in who he follows: @TFMKTS is one of the 185 people he currently follows ).
I think bonds are facing global supply pressures, at the same time as more and more people reduce their allocation to fixed income – more into equities, alternatives, option writing strategies for income, etc. I do think David could bring some new energy to the Treasury Department and his network and credibility could shift the narrative.
CDX moved a tad tighter on the week (also reflected in IG bond spreads). HYG and JNK inched higher (good for credit) as well. I’m not seeing any real reason to be materially concerned about credit, except there does seem to be decreasing excitement (if not appetite) to fund another chip or data center deal.
It makes perfect sense for credit to do a bit better if European sovereign debt is stabilizing, but since I don’t think we are done with being concerned about sovereign yields, we need to keep watching credit closely.
Credit weakness will transfer more directly to equities.
Bottom Line
At the margin, we are in better shape on “the state of yields” this weekend than we were last weekend, but we are not sounding the “all clear” yet by any stretch of the imagination.
On energy products, I’m worried that the Putin deal will turn out badly for our diesel aspirations, and that the apparent shift to “Legacy” over “midterms” for Trump does not bode well for energy prices this week. Nor does it help that Iran is ramping up attacks in the Strait. We continue to see a path to a “real” victory with Iran, but it will be a combination of the boycott, sanctions, economic, and military pressure to achieve that. All of which take time.