
Bank of America metals and mining analyst Lawson Winder shared his latest outlook for the space in a Friday note titled, "We like copper and uranium, while rates should keep a lid on gold prices."
Winder said his desk favors copper and uranium producers as global supply constraints collide with soaring power-grid demand, supporting higher prices for these commodities. He pointed out that higher US interest rates should keep the dollar bid while weighing on gold.
On single stocks, BofA downgraded Kinross Gold to Underperform and Alamos Gold to Neutral. Freeport-McMoRan remains BofA's top copper stock, while Cameco is its top uranium pick.
For base metals, Winder said copper is the strongest industrial metal. He said constrained supply and long-term electrification demand support higher prices. His desk raised its 2026 average copper forecast by 3% to $13,278 a ton and increased its long-term estimate by 20% to $13,578, adding that prices could average $15,250 in 2027.
He lifted his Freeport price target to $87 from $80, citing progress in the Grasberg operational turnaround and prospects for production growth.
Uranium is another favorite for BofA analysts, even though they cut their 2026 average estimate for the radioactive metal used in nuclear fuel rods to about $97 a pound. They maintained their 2027 projection near $130, roughly 45% above the spot price cited in the report.
Cameco offers one of the top exposures to both uranium prices and nuclear buildout through its 49% stake in Westinghouse, the analyst said. He maintained his "Buy" rating and a $133 price target on one of the world's largest providers of uranium fuel for clean nuclear power.
Here's the full list of precious metals, industrial and base metals, and steel stocks in Winder's coverage universe:
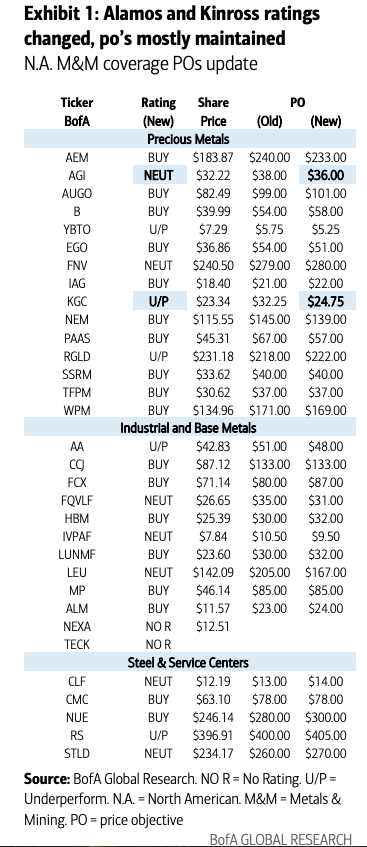
Extended explanation of the coverage universe:
Agnico Eagle Mines (AEM)
Our $233 per share price objective is based on Agnico Eagle trading at 2.00x times our estimated NAV (current net debt position plus a mining asset DCF utilizing a 5% WACC). Historically, North American gold producers have traded between 1 and 2 times NAV, with 1.75-2.0 times being accorded to the organically growth-oriented gold producers such as AEM.
Risks of this price objective not being attained are commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, and political risk in the countries the company operates in. Upside risks are commodity price strength, better-than-forecast operating performance and favorable changes in the political environment in the regions where it operates.
Alamos Gold (YAGI / AGI)
Our price objective for Alamos Gold (AGI/YAGI) is US$36.00/C$51.00, based on the stock trading at 1.00x our estimated net asset value (NAV) and a 1.42 CADUSD FX rate. Historically, North American precious metal producers have traded between 1x and 3x NAV but more recently between 1x and 2x, with unhedged, growth-oriented producers occupying the upper end of the range and Junior and Mid-tier producers trading historically at a discount to the senior producers.
Upside risks to our PO are a higher-than-forecast gold price, a lower-than-forecast CADUSD FX rate, exploration success at Island, Mulatos and Young-Davidson, better-than-expected synergies at Magino, advantageous changes to the regulatory and/or tax regimes in the jurisdictions in which they operate, and the potential for AGI to be acquired at a premium valuation.
Downside risks are a lower-than-forecast gold price and higher-than-forecast CADUSD FX rate, risks of the Argonaut transaction not receiving regulatory approval, operational challenges with the Magino mine, risks associated with undertaken M&A (such as with respect to integration of assets), and unforeseen operating and development issues at other assets.
Alcoa Corporation (AA)
Our price objective of $48.00 for AA is based on 4.0x 2026E EV/EBITDA, 3.5x 2027E EV/EBITDA and 1.0x net asset value (NAV), with each value equally weighted. The 4.0x 2026E EV/EBITDA target multiple is below the lower end of the global aluminum producer peer average of 4-5x due to our more bearish outlook for alumina from the BofA Global Research Commodities team as well as continued overhang related to Section 232 tariffs, San Ciprian/Alumar restart and Western Australia bauxite permits. The 3.0x is also below AA's historical trading average (since 2016 separation) of 5x. The 3.5x 2027E EV/EBITDA multiple is lower than the 2026E multiple to account for time value. The 1.0x price to NAV (P/NAV) target multiple is in line with our broad NA metals and mining coverage.
Downside risks to our price objective are 1) aluminum price weakness, 2) extended delays in getting its bauxite mine approvals in Western Australia, 3) pension liabilities, 4) higher raw materials costs including electricity, oil, caustic soda, coke, and pitch, 5) power contract negotiation risk (electricity is a large cost component), 6) power disruption risk and other unforeseen weather-related risks, 7) political, regulatory and country risks, 8) unfavorable currency changes including in the BRL, CAD, EUR, ISK and NOK, and 9) the removal of protective tariffs in markets.
Upside risks to our price objective are 1) higher aluminum prices, 2) better-than-expected cost containment, and 3) global demand growth.
Almonty Industries Inc (ALM)
Our $24 price objective (PO) is based on 8.0x 2027E EV/EBITDA, 7.5x 2028E EV/EBITDA, and 1.0x P/NAV. We think the target multiples are conservative as they are discounted to critical mineral stocks that trade around 25x 2026E EV/EBITDA. At 8.0x 2027E EV/EBITDA, our target multiple would be in-line with historical trading average of the copper stocks (which we consider more industrial metal stocks but have some elements of critical mineral stocks), and a substantial discount to the current 25x trading multiple of the critical mineral stocks). Our 7.5x 2028E EV/EBITDA target multiple is a standardized (0.5x) discount to 2027E to account time value risk. While our 1.0x P/NAV target multiple is typical for copper and critical mineral stocks, it does reflect a substantial discount to where both groups are now trading.
Upside risks to our PO are higher than expected tungsten prices (whether accelerating demand or continued supply challenges), weaker local currencies than expected that reduce USD operating costs (i.e. EUR, KRW), the build-out of key projects that are not included in our current forecasts (Los Santos, Valtreixal, Gentung), and the potential for ALM to become the subject of an acquisition.
Downside risks to our PO are lower than expected tungsten prices (whether slowing demand or greater than expected supply), stronger local currencies than expected that increase USD operating costs (i.e. the EUR and KRW), and operational challenges.
Aura Minerals (AUGO / XEDTA)
Our price objective for Aura Minerals is US$101.00 and R$169.00 per share, and is based on the stock trading at 1.35 times our estimated net asset value (NAV). Our NAV is based on a 5% discount rate and a long-term gold price of $3,500/oz. In recent history, North American precious metal stocks have traded between 1 and 2 times NAV, with unhedged, growth-oriented producers with solid balance sheets occupying the upper end of the range. Our 1.35x NAV for AUGO is at a premium to the average of Intermediate/Junior (Jr) peers in our coverage to recognize its peer leading production growth profile.
Upside risks to our price objective are stronger-than-forecast commodity prices, lower than expected costs, positive regulatory, permitting or operating developments and significant success in exploration.
Downside risks to our price objective are unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs, and delays in the development of its growth projects.
FX and controlling shareholder influence could be risks in either direction.
B2Gold Corp (YBTO / BTG)
Our price objective for B2Gold (BTG/YBTO) is US$3.75/C$5.25 based on the stock trading at 0.75x our estimated net asset value (NAV). Historically, North American precious metal stocks have traded between 1.0x and 3.0x NAV and between 1.0x and 2.0x more recently with a median of 1.25-1.50 times, with unhedged, growth-oriented producers occupying the upper end of the range. We use a 0.75x NAV multiple for BTG vs. mid-tier gold producer peers' target multiples at 0.75x-1.25x given higher execution risk.
Downside risks to our BTG valuation are: 1) political risk from Mali 2) mine plan estimates in excess of BTG reserves, 3) lack of commodity diversification, 4) mine plans that are based on outstanding permits or approvals, 5) unfavorable changes in currencies, 6) unforeseen increases in in put costs such as the price of oil and labor, 7) the possibility it could lose its social license to operate at any of its mines or projects 8) potential cuts to the dividend or reduced capital return and 9) issues with the ongoing construction and ramp-up of the Goose project. Upside risks are a higher gold price, the possibility for BTG to be acquired and unexpected exploration success. 10) Our gold price forecast is also a risk to our BTG valuation/forecasts.
Barrick Mining (B)
Our price objective (PO) for Barrick Gold is $58.00 per share and is based on the stock trading at 1.25x our estimated net asset value (NAV). Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with unhedged, growth-oriented producers with assets located in relatively geopolitically stable regions occupying the upper end of the range. Preventing us from assigning a higher target P/NAV multiple is Barrick's stable gold output. Downside risks to our price objective are: commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, political or legal challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects. Upside risks are stronger than expected commodity prices, better than expected production and cost control.
Cameco Corporation (YCCO / CCJ)
Our C$190 ($133) PO is based on 1.0x our NAV and 35.0x 2026E & 34.5x 2027E EV/EBITDA (all 3 equally weighted). We use a CADUSD FX rate of 1.42. The 35.0x 2026E EV/EBITDA is above its long-term average of c.15x, but below the long-term peak of c.40.0x that occurred when nuclear energy growth was last very strong. The 34.5x for 2027E is a slight discount to 35.0x used for 2026E given time-related risk. The 1.0x P/NAV is above the longer-term average of c.0.9x but below peak of 1.35x. We think 1.0x is justified given Cameco's world-class tier one assets in favorable jurisdictions (Canada) & potential exploration upside partially offset by voluntary idling of one of those tier-one assets (but is in the process of restarting).
Downside risks: 1) slower-than-expected global energy demand growth, 2) continued push-out of a Japanese nuclear fleet restart, 3) any worsening in sentiment toward nuclear or more favorable sentiment toward alternative power fuel sources, and 4) any production problems at Cameco's only operating mine, Cigar Lake.
Upside risks: 1) additional potential mine disruptions that may further improve supply-demand dynamics, 2) better pace of reactor development in key future demand countries (China, Japan, and India), 3) more stringent carbon emissions restrictions in key countries, encouraging nuclear power as an environmentally friendly base line energy source, 4) a material rise in natural gas prices making nuclear power generation competitive in the US.
Centerra Gold (YCG / CGAU)
Our price objective for Centerra Gold is C$22.75 per share and US$16.00 per share, based on the stock trading at 0.75x our estimated net asset value (NAV). Historically North American precious metal stocks have traded between 1 and 3 times NAV, with a median of 1.50 times over the past nine years (and 2.00 times longer-term), with unhedged, growth-oriented producers occupying the upper end of the range.
Downside risks to our price objective for Centerra Gold are commodity price weakness, delays in the development of its growth projects and the potential for additional operating issues at Öksüt. Upside risks to our price objective are gold and molybdenum prices rising, unexpected exploration success at any of the assets, and a favorable renegotiation of its gold/copper stream on Mt. Milligan.
Centrus Energy Corp. (LEU)
Our price objective (PO) of $167 per share is derived based on 2.5x our estimated net asset value (NAV). The 2.5x 2026E NAV target multiple is a premium to the nuclear fuel supply peers to account for barriers to entry, its emerging next generation nuclear fuel growth business, strong enrichment market fundamentals to which its peers have minimal exposure, and U.S. government support, that is now being realized via the early 2026, $900m DoE funding award.
Downside risks are:1) lower than forecast enrichment pricing, 2) loss of access to enriched uranium product, 3) unexpected restrictive regulatory changes, possibly including sanctions, 4) shipping disruptions, and 5) technical disruptions.
Upside risks are: 1) higher than forecast enrichment pricing, 2) unexpected government financial and/or regulatory support, 3) a potential acquisition, and 4) faster than expected deployments of small and advanced modular reactors.
Cleveland-Cliffs (CLF)
Our $14.00 PO is based on 7.0x 2026E EV/EBITDA, 6.5x 2027E EV/EBITDA and 1.0x net asset value, with each value equally weighted. The 7.0x 2026E EV/EBITDA target multiple is higher than its historical trading average of 7.4x and is more in line with that of its key steel peers given an emerging recovery in US auto production and CLF's substantial automotive exposure relative to public peers.
Downside risks: 1) new capacities pressuring steel prices & margins, 2) obsolescence of its capacity relative to newer supply forcing closures, 3) higher-than-expected capex or interrupted operations to address older mills or environmental liabilities, 4) union representation may keep labor costs high relative to peers, 5) underfunded pension/health care position & high leverage, 6) risks to auto sector demand, including switching to aluminum & alternative materials, 7) higher imports and/or, 8) changes to trade policy.
Upside risks: 1) better steel demand than we anticipate, 2) steel price outperformance, especially if driven by raw materials as CLF is largely vertically integrated, 3) Further reduction in underfunded pension & OPEB liability, 4) resumption of the dividend, 5) better auto negotiating position for longer, and 6) sustained/higher barriers to imported steel. 6) More earnings accretion from agreement with major global steel producer.
CMC (CMC)
Our $78 per share price objective for Commercial Metals (CMC) is based on a blended 6.5x FY26E EV/EBITDA, 6.0x FY27E EV/EBITDA and 1.0x our NAV. The 6.5x 2026E EV/EBITDA target multiple is higher than its historical trading average of 6.1x to reflect the market rerating. However, the 6.5x multiple is below the target multiples used for other mini-mill peers (7.5x-8.0x) given its less diverse products / end-markets. This is partly offset by CMC's leverage to infrastructure (which is set to see strong growth from a significant increase in federal spending) and reshoring demand.
Upside risks to our price objective are: 1) better-than-expected construction / reshoring demand, 2) higher steel pricing, 3) better-than-expected pricing power in global long products that support pricing and limit imports, 4) additional trade relief, 5) cash deployment for organic or inorganic growth.
Downside risks to our price objective are: 1) sluggish demand due to delay in federal funding and/or tightened credit availability for private projects, 2) lower steel pricing, 3) execution risk related to Tensar and new micro-mills, 4) any rollback of trade relief, particularly related to Section 232, 5) threat of lower priced imports and 6) potential medium term oversupply from various new entrants in the domestic rebar market.
Eldorado Gold (EGO / YELD)
Our price objective of $51.00 (C$72.00) is based on the stock trading at 1.25x times its estimated net asset value (NAV). Historically, North American precious metal stocks have traded between 1 and 3 times NAV over the last five years, with a median of 1.50 times (and 2.00 times longer-term) and with unhedged, growth-oriented producers occupying the upper end of the range. We value EGO below the lower end of the valuation range due to higher political risk for operating in Greece and Türkiye.
Downside risks to our price objective for Eldorado Gold are commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects.
Upside risks are a higher-than-expected gold price, a more hospitable regulatory environment in the jurisdictions where the company operates (in particular, Greece), more favorable foreign exchange rates than now projected, and better-than-expected operational results.
First Quantum Minerals (YFM / FQVLF)
Our C$44.00 and US$31.00 price objectives are based on a 9.5x 2026E EV/EBITDA, 9.0x 2027E EV/EBITDA, and 1.00x our NAV estimate, reflecting the long-term value of the suspended Cobre Panamá mine (we assume mine restarts in late-2027E) and the steps taken to strengthen the balance sheet.
Upside risks are stronger than forecast copper prices, early resumption of FM's development projects (Cobre Panamá), favorable local currency changes that lower USD costs, and the potential for First Quantum to become an acquisition target.
Downside risks to our PO are a weaker-than-expected global economy that could impede metal demand growth expectations, affecting our commodity price forecasts. In addition, sovereign risks in Zambia (i.e., challenging geopolitical environment, developing infrastructure) and Panamá (mining a newer industry), ramp-up issues at Cobre Panamá, stronger than forecast local currencies that increase USD costs, labor action, and weather could also impact our FM valuation and PO.
Franco-Nevada (YFNV / FNV)
Our price objective for Franco-Nevada is C$398 (US$280) per share, based on the stock trading at 2.65x our estimated net asset value (NAV) on a cash-adjusted basis and a USD/CAD FX rate of 1.42x. Historically, North American precious metal streaming stocks have traded between 1.50 and 3.50 times NAV, with growth oriented streaming companies at the top end. Based on its strong balance sheet and low-cost asset base, we believe Franco-Nevada deserves a premium multiple. Franco-Nevada also benefits from an experienced management team.
Upside risks to our PO are substantially higher commodity prices, higher-than-expected output at the royalty assets, and/or higher reserves.
Downside risks are commodity price weakness and unforeseen operating problems at the mines on which its royalties are based.
Freeport-McMoRan (FCX)
Our $87.00 per share price objective blends 11x 2026E, 10.5x 2027E EV/EBITDA and 1.0x our net asset value (NAV). The EV/EBITDA target multiples are above the 8.0x historical average for copper producers covered by BofA Global Research to reflect the impact from temporary lower volumes at Grasberg and our bullish view for Copper. Our P/NAV multiple of 1.0x is in line with most of the copper producers covered by BofA Global Research but is arguably conservative given several potentially value-enhancing growth options that we do not currently model. These include a new mill at El Abra, a mill expansion at Bagdad and low-grade leaching.
Downside risks to our price objective are 1) global economic weakness, 2) Operating disruptions, 3) execution risk at its cost-cutting or expansion programs, 4) stricter or unfavorable regulatory or environmental regulations, particularly at its Indonesian operations, 5) other factors pressuring prices of the commodities it produces and 6) unfavorable currency moves.
Upside risks are 1) better-than-expected copper and gold prices, 2) a more accommodating operating environment in Indonesia and 3) further cost-cutting progress.
Hudbay Minerals (YHBM / HBM)
Our C$45.50 (US$32.00) per share price objective for Hudbay Minerals (YHBM/HBM) is based on a 8.5x 2026E EV/EBITDA multiple, 8.0x 2027E EV/EBITDA multiple and 1.0x our net asset (NAV) estimate, weighted equally to each. Since 2005, the global copper producers have traded in an EV/EBITDA range from 2.0x to 13.0x with HBM trading at a discount. For HBM, we use a below peer target multiple given a less diverse asset base than average (just two copper mines and one gold mine) partly offset by stronger average jurisdictional exposure.
Upside risks are stronger-than-forecast copper prices, favorable local currency changes that lower USD costs, the receipt of all permits for Rosemont with no legal challenges, a sooner than expected start of mining of the Pampacancha satellite deposit and the potential for HBM to be targeted for acquisition.
A downside risk to our PO is a weaker-than-expected global economy that could impede metal demand growth expectations, affecting our commodity price forecasts. Other downside risks are a delay in attaining surface access rights at Pampacancha, the political and regulatory climate in the jurisdictions in which HBM operates (Canada, Peru and the USA), stronger than forecast local currencies that increase USD costs, increases in general operating and development costs, labor action, weather and the inability to attain the needed permits to develop Rosemont, M&A risk.
IAMGOLD Corp. (IAG / YIMG)
Our price objective for IAMGOLD is US$22.00/C$31.50 per share, and is based on the stock trading at 1.35x times our estimated net asset value (NAV) and a 1.42 CADUSD exchange rate. Historically, North American precious metal stocks have traded between 1.50 and 3 times NAV, with a median of 2.00 times over the long-term, and with unhedged, growth-oriented producers with solid financial positions and low relative costs and located in stable mining jurisdiction occupying the upper end of the range. We ascribe a moderate P/NAV multiple to IAMGOLD to reflect our forecast for higher than average political risk in Burkina Faso, execution risks at the Cote Gold project, and higher cash costs and debt vs. peers. As the Cote Gold project in Canada ramp-ups, this should drive strong volume growth, lower costs and political risk, and ultimately drive deleveraging.
Upside risks: Gold price could surprise to the upside vs. our expectation. Potential positive developments in terms of exploration results and project execution.
Downside risks: Gold price could surprise to the downside vs. our expectations. Risks on project capital cost over-runs / schedule disappointment. We also consider the risk for unfavorable political developments, particularly in higher perceived political risk jurisdictions such as Burkina Faso.
Ivanhoe Mines (YIVN / IVPAF)
Our C$13.50 (US$14.50) price objective is based on 1.10x our net asset (NAV) estimate. The 1.10x price to net asset value (P/NAV) target multiple is at a modest premium to the current trading multiples of global copper producers to reflect its superior production growth, low relative unit costs, a strong balance sheet and solid copper optionality with the 100%-owned Western Foreland property.
Upside risks to our PO are stronger-than-forecast copper prices, faster-than-expected ramp-up of IVN's development projects (in particular, Kamoa-Kakula), the discovery of new mineral resources that become mining projects (Western Foreland has this potential), favorable local currency changes that lower USD costs, participation in the M&A backdrop
Downside risks to our PO are a weaker-than-expected global economy, jurisdictional risks in the Democratic Republic of Congo (DRC) and South Africa (i.e., tax regime changes, mining policy shifts, poorly defined legal frameworks, difficulty in obtaining social license, etc.), ramp-up issues at Kamoa-Kakula, input cost inflation, stronger-than-forecast local currencies that increase USD costs, labor action, and weather.
Kinross Gold (KGC)
Our price objective for Kinross Gold is $24.75 per share, and is based on the stock trading at 1.25 times our net asset value (NAV) estimate, reflecting production growth that is forecast to be slightly lower than the senior/mid-tier average. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with companies with declining production at the lower end of the range.
Risks to our price objective for Kinross Gold are commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, political or legal challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects or current mine expansions. On the upside, risks are stronger than expected commodity prices and an operating turnaround that exceeds our expectations in terms of timing and magnitude, and exploration success.
Lundin Mining Corp (YLUN / XLPRF)
Our C$45.00, US$33.00 and SEK304 per share price objectives for Lundin Mining are based on 11.5x and 11.0x EV/EBITDA multiples applied to our 2026E EBITDA and 2027E EBITDA and 1.0x applied to our net asset value (NAV) estimate. We apply a USDCAD FX rate of 1.42 and a USDSEK FX rate of 9.14. Since 2005, the global base metal producers have traded in an EV/EBITDA range from 2.0x to 13.0x, with Lundin trading at a discount to the average due to it being a smaller company. However, we see potential for a re-rating as LUN executes on its growth strategy including its transformative Vicuña project.
Downside risks to our PO are worse-than-expected economic performance that could impede our metal demand expectations, impacting our commodity price forecasts. In addition, development and/or permitting delays, stronger than forecast local currencies that increase USD costs, worker strike action, several possible technical missteps and weather could also impact our Lundin valuation and PO.
Upside risks are higher-than-forecast commodity prices as well as weakening local currencies, substantial exploration success leading to longer mine lives and/or higher margin ounces, the potential for LUN to become an acquisition target.
Lundin Mining Corp (LUNMF)
Our C$45.00, US$32.00 and SEK304 per share price objectives for Lundin Mining are based on 11.5x and 11.0x EV/EBITDA multiples applied to our 2026E EBITDA and 2027E EBITDA and 1.0x applied to our net asset value (NAV) estimate. We apply a USDCAD FX rate of 1.42 and a USDSEK FX rate of 9.14. Since 2005, the global base metal producers have traded in an EV/EBITDA range from 2.0x to 13.0x, with Lundin trading at a discount to the average due to it being a smaller company. However, we see potential for a re-rating as LUN executes on its growth strategy including its transformative Vicuña project.
Downside risks to our PO are worse-than-expected economic performance that could impede our metal demand expectations, impacting our commodity price forecasts. In addition, development and/or permitting delays, stronger than forecast local currencies that increase USD costs, worker strike action, several possible technical missteps and weather could also impact our Lundin valuation and PO.
Upside risks are higher-than-forecast commodity prices as well as weakening local currencies, substantial exploration success leading to longer mine lives and/or higher margin ounces, the potential for LUN to become an acquisition target.
MP Materials (MP)
Our $85 PO assumes a 25x multiple on our 2029E EBITDA, discounted back to today's money using MP's weighted average cost of capital of around 7.0%. The 25x multiple assigned is below its own historical average (of 34.2x) but in-line with its 2020-2024 average of 25.2x. The higher multiple vs peers recognizes 1) reduced execution risk, 2) expansion potential, 3) rising strategic premium, 4) and explicit Department of Defense (DoD) support. As the only integrated rare earth and magnetics producer in the Western Hemisphere, we continue to see MP as a unique investment vehicle for exposure. We are medium to long-term bullish neodymium-praseodymium (NdPr), MP's key upstream product.
Upside risks: 1) stronger EV and wind generation demand, 2) scarcity of other rare earths investment vehicles, 3) likely first-mover advantage in the vertical integration opportunity, 4) barriers to entry (Stage I and II), 5) potential for additional U.S. government financial support, 6) possible more collaborations with major EV makers, 7) the possibility that MP could be acquired, and 8) higher than expected rare earths pricing.
Downside risks: 1) execution of Stage II and III and cost containment, 2) higher China supply quotas, 3) new entrants, particularly outside of China., 4) increased competition in Stage III, 5) limited clarity on Stage III profitability, 6) rare earth magnet substitutes, and 7) slower EV adoption hurting demand.
Newmont Corporation (NEM / XNCRF)
Our price objective for Newmont is $139 (A$200) per share, and is based on the stock trading at 1.75x times our estimated net asset value (NAV). We assume a USDAUD exchange rate of 1.47. Our NAV is based on a 5% discount rate and a long-term gold price of $3,500/oz. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with a median of 1.50 times over the past three years (2.00 times longer-term), and with unhedged, growth-oriented producers with solid balance sheets occupying the upper end of the range. In the great gold rally of 2011, NEM's multiple peaked at 2.50x.
Upside risks to our price objective are stronger-than-forecast commodity prices, better than expected success at reducing costs and positive regulatory, permitting or operating developments. Downside risks to our price objective for Newmont are the inability to secure financing for expansion or development projects, unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects.
Nexa Resources (NEXA)
We have removed the investment opinion on the company's stock. Investors should no longer rely on our previous opinion or price objective.
Nucor (NUE)
Our price objective of $300 per share is based on 9.0x 2026E EV/EBITDA, 8.5x 2027E EV/EBITDA and 1.0x NAV, with each value equally weighted. The 9x 2026E EV/EBITDA target multiple is above its historical average of 7.3x to reflect potential upside from higher spot pricing and its highly variable cost structure, diversified product mix, strong volume growth potential (from multiple projects underway) and investment grade balance sheet with a disciplined capital return policy (minimum of 40% of net income).
Downside risks to our price objective are: 1) lower steel price and higher scrap costs squeezing margins, 2) weaker than expected demand especially in construction markets, 3) project start-up delays and cost overruns, and 4) M&A's which could be dilutive in the near-term.
Upside risks to our price objective are: 1) higher than expected steel prices, 2) lower than expected input costs, 3) lower import volumes, 4) more favorable trade policies, and 5) a stronger than expected economy.
Pan American Silver (PAAS)
Our price objective for Pan American Silver is $57.00, and is based on the stock trading at 1.75x our estimated net asset value (NAV) on a net investments-adjusted basis (i.e. the 1.75x multiple is applied to the asset value and then the value of the equity investments is added to that with an effective 1.0x multiple applied). Our NAV is based on a 5% discount rate for all assets, except Escobal for which we use 7.5%. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with silver producers generally trading at a discount to gold producers.
Upside risks to our price objective are higher than expected commodity price forecasts, a change in the regulatory/permitting environment in the Chubut province of Argentina where Pan American's dormant Navidad project is located, operating results that exceed expectations and lower than expected capital costs.
Downside risks to our price objective are unforeseen operating issues, realized commodity prices that are below our forecast, regulatory issues (including tax, environmental and permitting) that cause financial results to differ from our forecast, and higher than expected capital costs.
Reliance, Inc. (RS)
Our $405 per share price objective for Reliance Inc. (RS) is based on 11.5x 2026E EV/EBITDA, 11.0x 2027E EV/EBITDA and 1.0x NAV, with each value equally weighted. The 11.5x 2026E EV/EBITDA target multiple is above its historical trading average of 8.3x to account for improved business model with higher long-term sustainable gross profit margin of 29-31% versus 25-27% in 2015/16 and potential growth through M&A.
Downside risks to our price objective are: 1) a sharp correction in prices (carbon steel, stainless and aluminum), 2) weaker than expected macro, leading to lower metal demand, 3) higher imports and 4) execution risk related its acquisition strategy.
Upside risks to our price objective are: 1) aggressive buybacks or dividend increases, 2) higher metal prices, 3) more attractive consolidation opportunities and 4) a better demand environment.
Royal Gold (RGLD)
Our price objective for Royal Gold is $222 per share, which is based on the stock trading at 2.00x our adjusted net asset value (NAV), valuing net cash cost 1:1. Our net asset value (NAV) is based on a 5% discount rate. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with unhedged, growth-oriented producers occupying the upper end of the range. Given Royal Gold's status as a royalty company as opposed to an operator, our target valuation multiple reflects its good cash flow-generating ability.
Upside risks to our PO are substantially higher commodity prices, higher-than-expected output at the royalty assets, and/or higher reserves at the royalty assets. Downside risks are a weaker gold price, problems at the operations, and no exploration success.
SSR Mining Inc. (SSRM / YSSRM)
Our price objective for SSR Mining is $40.00 (C$56.00) per share, and is based on 1.25x our adjusted estimated net asset value (NAV). Our NAV is based on a 5% discount rate (consistent with the vast majority of gold operations within our North American precious metals coverage) and long-term gold price forecast of $3,500 per ounce. Historically, North American precious metal stocks have traded between 1 and 3x NAV, with a median of 1.00x over the past three years (2.00x longer-term). Our target multiple reflects the enormous uncertainty surrounding the outcome of the heap leach pad slide at the Copler mine balanced by stronger North American operations.
Upside risks to our price objective are stronger-than-forecast commodity prices, better-than-expected success at reducing costs and positive regulatory, permitting or operating developments.
Downside risks to our price objective for SSR are the inability to secure financing for expansion or development projects, unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects.
Steel Dynamics (STLD)
Our $270 per share price objective for Steel Dynamics (STLD) is based on 8.5x 2026E EV/EBITDA, 8.0x 2027E EV/EBITDA and 1.0x NAV, with each value equally weighted. Our 8.5x target EV/EBITDA multiple is higher than its historical trading average of 6.6x to reflect potential upside from higher spot pricing and its industry leading utilization rate, highly variable cost structure, leading value-add product portfolio, investment grade balance sheet and unique exposure to higher margin downstream business via its aluminum rolling mill. At spot pricing, the implied valuation multiple is closer to 8.0x, still high historically.
Upside risks to our price objective are: better than expected macro leading to stronger steel pricing and spreads than we forecast, continued Fabrication tailwind, aggressive shareholder returns, more protective trade policy, and lower imports.
Downside risks to our price objective are: lower steel and metal spreads, project delays, lower than expected demand, higher imports, and excess industry supply.
Teck Resources (YTECK / TECK)
We have removed the investment opinion on the company's stock. Investors should no longer rely on our previous opinion or price objective.
Triple Flag Precious Metals Corp. (YTFPM / TFPM)
Our C$53.00 ($37.00) per share PO for TFPM is based on a target valuation multiple of 2.00x our estimated NAV. The multiple is a slight discount to the senior royalty & streaming peers giving consideration to TFPM's smaller market cap and liquidity, and less diversification by geography, commodity and operator, partly offset by above average margins and attributable GEO production growth. The multiple is at the high end of the range for the gold producer peers given the attractive relative investment characteristics of the royalty & streaming business model (precious metals exposure with insulation from opex and capex inflation and upside from production growth and exploration success.
Our NAV estimate is based on a 5% real discount rate and long-term gold and silver prices of $3,500/oz and $42.00/oz (starting in 2031E).
Downside risks to our PO are: 1) a lack of input the operation of portfolio assets, 2) competition from a growing royalty and streaming sector 3) precious metal price volatility, 4) asset investments in non-investment grade emerging markets, 5) concentrated ownership structure, 6) ramp up delays at development projects.
Upside risks are: 1) higher than expected gold and silver prices, 2) future exploration discoveries and unexpected expansions at mines in the portfolio, 3) a potential acquisition of TFPM.
Wheaton Precious Metals (WPM)
Our price objective for Wheaton is $169.00 per share, and is based on the stock trading at 3.25x times our estimated net asset value (NAV). Our NAV per share is based on a 5 percent discount rate. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with a median of 2.00 times longer-term (1.50 times in the last three years), and with royalty/streaming companies occupying the upper end of the range.
Risks to our price objective for Wheaton are continued commodity price weakness, unforeseen operating problems at the mines on which its silver streams are based, financing challenges, political or legal challenges in the regions in which the mines operate, and delays in the development of projects for which the company silver streams.
Professional subscribers can read the full metals note here at our new Marketdesk.ai portal.